Major Banks Drop Fraud Protection for AI Agent Users
Citibank, JPMorgan Chase, Bank of America and other major US banks now hold customers liable for losses from third-party AI agents, while exempting their own in-house assistants.
Listen to this article
4 chapters
In this article
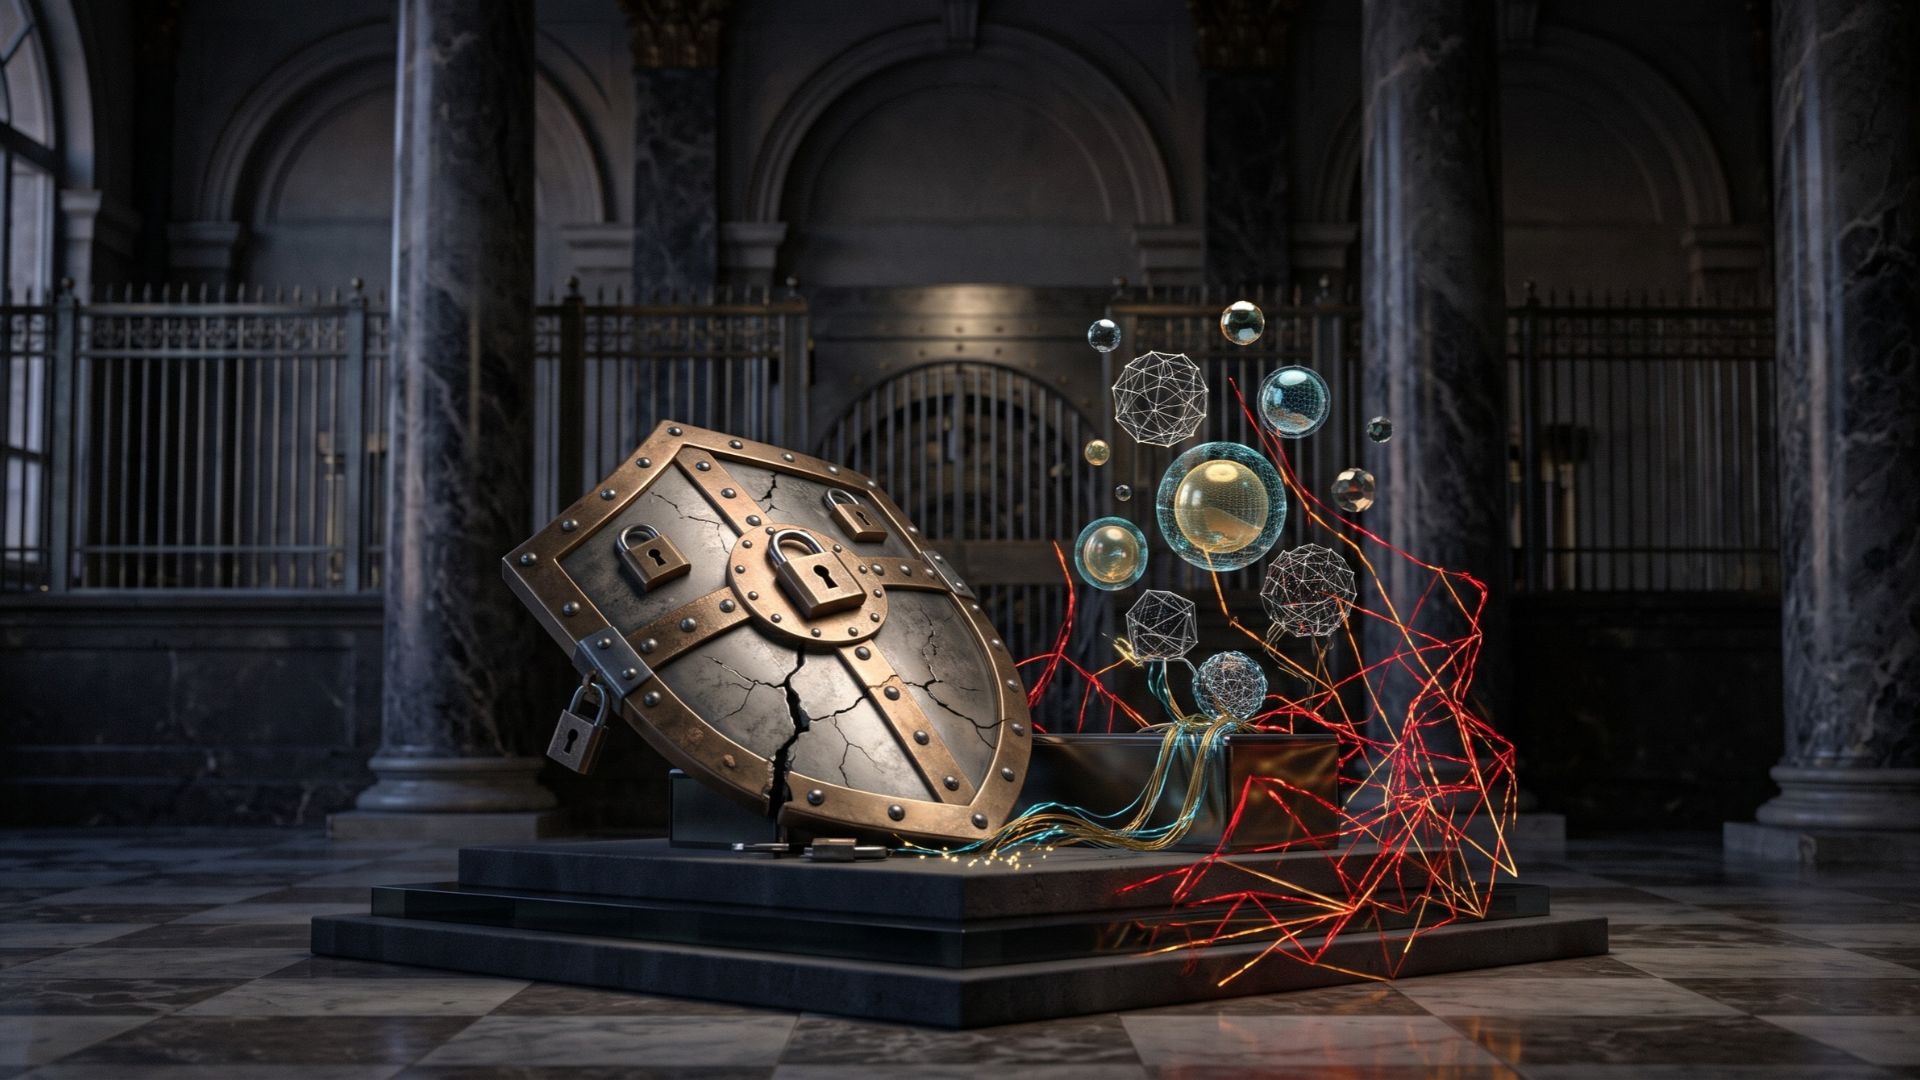
Handing over your online banking credentials to an autonomous AI assistant might soon cost you your consumer fraud protections. Several of the largest financial institutions in the United States, including Citibank, JPMorgan Chase, Bank of America, PNC, and Citizens, have quietly rewritten their terms of service to shift financial liability directly onto customers who link third-party AI tools to their accounts. Under these updated user agreements, if an external AI agent makes a costly mistake, executes an unauthorized transfer, or suffers a data breach that exposes your login details to hackers, the bank will not reimburse your losses.
The New Liability Shift
Citibank, the third-largest commercial bank in the U.S., introduced a sweeping update to its Online User Agreement this week that treats any activity conducted through a third-party AI agent as directly authorized by the customer. The policy goes far beyond simple user error. If an external AI platform is compromised and leaks a customer's credentials, Citibank considers any subsequent actions by malicious hackers to be the customer’s sole financial responsibility.
Citibank is hardly acting alone. JPMorgan Chase and Bank of America rolled out comparable restrictions in October, barring outside AI tools from logging in with customer credentials while holding users accountable for any fallout. PNC updated its terms the same day as Citi; Citizens issued direct email warnings to account holders; and Wells Fargo’s revised agreement, stating that AI agent usage is strictly at the customer's own risk, is set to take effect later this month.
Security Risks Meet Competitive Threats
While banks frame these updates around cybersecurity and the unpredictability of autonomous software, the policy shift also reflects a fierce battle over who controls the customer relationship. AI startups and frontier labs are racing to build personal finance tools for analyzing spending habits, paying bills, and optimizing investments.
For traditional banks, autonomous agents pose a major threat to core revenue streams. Smart AI assistants can easily spot hidden fees or automatically sweep idle cash out of low-interest checking accounts into higher-yielding alternatives, a shift analysts estimate could cost banks tens of billions of dollars annually. By restricting third-party access, banks are protecting their margins while steering users toward their own ecosystems. Notably, Citibank’s revised terms explicitly exempt native AI tools built into Citi’s own apps, assuring customers they face no extra liability when using the bank's in-house assistants.
A Cautious Turn for Agentic Finance
The banking crackdown highlights a growing friction between ambitious AI developers and risk-averse service providers. Rather than welcoming autonomous agents into legacy financial infrastructure, institutions are forcing a clear boundary between read-only data analysis and actual transaction execution. Even major AI labs are treading carefully; Anthropic’s recently launched personal finance tool is strictly "read-only" by design, preventing it from moving, managing, or investing user funds.
For users accustomed to Web3 and self-custody wallets where guarding private keys and bearing sole responsibility for smart contract approvals is standard practice, this liability shift feels familiar. Traditional banking, however, has long relied on institutional safety nets and fraud reversal guarantees. Although federal regulations like Regulation E still offer statutory protections for certain unauthorized electronic transfers, everyday consumers linking autonomous AI agents to their bank accounts now face a stark reality: when you delegate your banking keys to an algorithm, you assume the risk if something breaks.
The Morning Brief
Start every day knowing what matters in tech
Six stories chosen by our editors, in your inbox at 06:00 UTC. Free.
Instant notifications in this browser when big news breaks. No email needed, and you can turn them off any time.
See more Blockrora in Google
Make us a preferred source and our stories show up more often in Top Stories.
Editor and Writer at Blockrora. Backed by years in mainstream tech and health tech development, Lauren covers digital health, tech adoption, and the societal shifts shaping the web. Wellness advocate and coastal wanderer.
More from Lauren →